Paul Rippon: From Banking Pioneer to Investor and Entrepreneur
How the Monzo co-founder built a career across banking, challenger finance, alpaca farming and growth investment

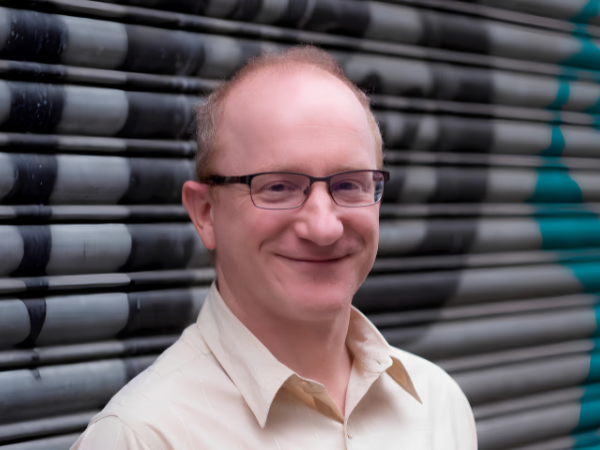
Paul Rippon is a British banker, entrepreneur, investor and business operator best known as a co-founder of Monzo and Starling Bank. After more than three decades in financial services, he moved from frontline banking into challenger banking, farming and investment. He is now the founder of Rippon Capital, an operator-led investment firm focused on providing growth capital to UK businesses.
Rippon’s professional profile describes him as an “operator, investor, catalyst”, reflecting a career built around starting, developing and supporting businesses. His LinkedIn profile identifies him as a Monzo co-founder and lists Rippon Capital among his current professional activities.
His story is unusual because it extends well beyond fintech. Alongside his banking career, Rippon and his wife, Debbie, built an alpaca farming business in Northumberland, turning an unexpected lifestyle change into another substantial business venture.
Paul Rippon Age
Paul Rippon was born in April 1971, according to Companies House records. That makes him 55 years old in 2026. The same official record identifies him as British and resident in the United Kingdom.
His age is particularly relevant when looking at the length of his career. By the time he became associated with Monzo, he already had decades of experience in financial services rather than coming directly from a technology background.
In 2020, when he left Monzo to concentrate more heavily on Barnacre Alpacas, contemporary reporting stated that he was 48 and had already spent 27 years working in financial services.
Early Career and Banking Background
Before becoming associated with Britain’s digital banking revolution, Rippon built a long career in traditional financial services.
His career included work with major banking organisations such as NatWest, Northern Rock and AIB, before he moved into the emerging challenger-bank sector. His experience gave him a strong background in risk, credit, banking operations and financial services management.
His education also reflects that banking background. His LinkedIn profile lists ifs University College, where he completed professional banking qualifications, including Associate and Fellow of the Chartered Institute of Bankers. It also records an academic programme in learning and teaching.
That combination of practical banking experience and professional education became important when the UK financial sector began moving towards technology-led challenger banks.
Paul Rippon and Starling Bank
One of the most important chapters in Rippon’s career was his involvement with Starling Bank.
Rippon Capital identifies him as a co-founder of Starling Bank, placing him among the people who helped develop one of Britain’s prominent digital banking businesses.
Starling was part of a wider transformation in British banking. New technology made it possible for financial institutions to build services around mobile applications, modern infrastructure and digital-first customer experiences.
Rippon’s traditional banking knowledge was therefore combined with the demands of building a modern financial institution. This experience would later contribute to his role in creating another major challenger bank.
Paul Rippon and Monzo
Rippon is perhaps most widely recognised for being a co-founder of Monzo.
Monzo was founded in London in 2015, with Rippon among the founding team. Research into the company’s founding identifies him as the former chief risk officer alongside Tom Blomfield, Gary Dolman, Jason Bates and Jonas Templestein.
The business became one of the UK’s best-known digital banking brands. Its development coincided with growing consumer demand for mobile banking, instant notifications, app-based money management and simpler digital financial services.
Rippon’s contribution was rooted partly in his banking and risk experience. Rather than approaching financial technology solely from a software perspective, his background included the regulatory, operational and risk considerations involved in establishing a bank.
Why Did Paul Rippon Leave Monzo?
Rippon eventually decided to step away from Monzo and devote more time to his family’s alpaca business.
In January 2020, ITV reported that he had left the company after describing the demands of building a rapidly growing bank and his desire to enjoy life and spend more time with his wife and farm.
His departure became unusual business news because his next chapter was far removed from fintech. Instead of moving immediately to another major financial institution, he became increasingly involved in Barnacre Alpacas, a family business in Northumberland.
Paul Rippon Family
Paul Rippon is married to Debbie Rippon, with whom he runs Barnacre Alpacas. The couple’s farming story began after they developed an interest in alpacas and spent several years researching how they could establish their own operation.
Barnacre Alpacas describes Paul and Debbie as a husband-and-wife partnership dedicated to breeding alpacas and producing alpaca-related products. Their operation developed substantially after its foundation in 2007.
Rippon has also spoken publicly about their journey from working-class roots in Nottingham to establishing a rural life in Northumberland. His LinkedIn profile has described the farm as a long-running family business and personal passion.
There is considerably less reliable public information about other immediate family members, including children. For that reason, claims about his wider family should not be treated as established unless supported by a reliable source.
Barnacre Alpacas and a Different Kind of Business
Barnacre Alpacas became an important part of Rippon’s life after his departure from Monzo.
The farm, run by Paul and Debbie, developed from their initial purchase of three pregnant alpacas into a much larger operation. The business now includes alpaca breeding, farming-related activities and handmade alpaca knitwear.
Rippon’s farming experience also demonstrated another side of his approach to business. In interviews and public posts, he has discussed the practical responsibilities involved in animal care, farm management and running a business outside the financial sector.
The move from digital banking to farming became one of the more distinctive aspects of his public biography.
Paul Rippon Net Worth
Paul Rippon’s exact current net worth has not been reliably disclosed in public sources. Therefore, a precise figure should not be presented as fact.
His financial position is linked to a long banking career, his involvement in major fintech businesses and subsequent private investments. Rippon Capital says he has invested personal capital in companies including Plend, Lendable and First Portfolio.
In a recent statement published on LinkedIn, Rippon said he had made a seven-figure personal investment in Plend across debt and equity. He also described two earlier investments as complete losses, illustrating that his investment record has included both successful and unsuccessful ventures.
The Evening Standard previously included Rippon in its technology rich-list coverage, but that historical estimate should not be confused with a verified 2026 net-worth figure.
Consequently, the most accurate description is that Rippon is an experienced entrepreneur and investor with substantial business interests, while his exact personal wealth remains private.
Paul Rippon Wikipedia
There does not appear to be a dedicated Paul Rippon Wikipedia biography corresponding to the UK fintech entrepreneur in the current sources reviewed.
This is worth mentioning because searches for “Paul Rippon Wikipedia” can create confusion with other people who share the same name.
For reliable biographical information, primary sources such as Rippon Capital, Companies House and Rippon’s professional profile provide more useful evidence about his current career and business activities.
Paul Rippon and Rippon Capital
After his banking and farming chapters, Rippon returned to investment through Rippon Capital.
The firm describes itself as an operator-led investment business founded on more than 30 years of banking experience. Its approach combines capital with practical involvement, using debt, equity and operator expertise to support businesses.
The firm’s recent material identifies Plend as its first major investment. Rippon has explained that his relationship with the company began in 2022 through personal investments before Rippon Capital later took a controlling stake.
This represents a natural progression in his career: from managing banking risk, to helping build challenger banks, and eventually using his experience and capital to support other businesses.
Conclusion
Paul Rippon’s career has taken an unusual route through British banking and entrepreneurship. His experience began with traditional financial services before moving into the challenger-bank revolution through Starling Bank and Monzo.
His decision to leave Monzo and become deeply involved in Barnacre Alpacas added an unexpected chapter to his professional story. Today, his focus has returned to investment through Rippon Capital, where he combines financial experience with hands-on business involvement.
While details such as his exact net worth and wider family life remain private, the public record clearly establishes a career spanning banking, fintech, farming and investment. At 55, Paul Rippon continues to build on more than three decades of experience across the financial and entrepreneurial landscape.


