Setu Kamal: Career, Age, Family, Net Worth and Legal Career Explained
A detailed look at the tax barrister’s professional background, expertise, public profile and the major legal and regulatory developments surrounding him

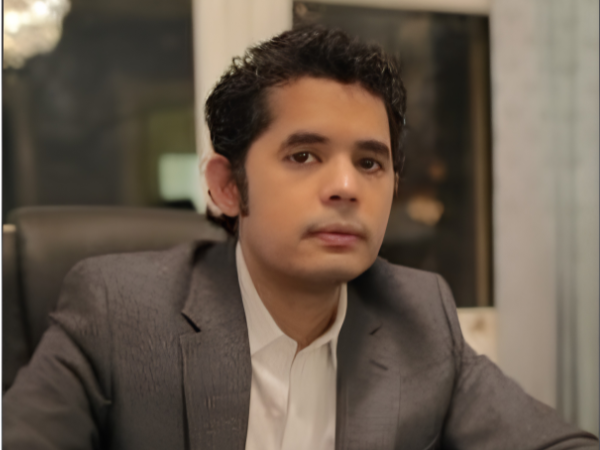
Setu Kamal is a British tax barrister who was called to the Bar in 2004 and built a career specialising in tax and Chancery law. He has been associated with Old Square Tax Chambers at Lincoln’s Inn and has contributed to major tax publications, including Whiteman & Sherry on Income Tax. His professional career has also involved significant tax litigation. In 2026, his name became prominent following a High Court ruling concerning an £8 million libel claim and a separate interim suspension from practising as a barrister.
Who Is Setu Kamal?
Setu Kamal is a British barrister whose professional career has centred on taxation and related areas of law.
Public professional records show that he was called to the Bar in 2004. Court records have also identified him as being associated with Old Square Tax Chambers, Lincoln’s Inn, London. His professional profile has described more than two decades of experience in tax and corporate-law matters.
His work has covered complex issues involving individuals, businesses and tax structures. Over the years, his name has appeared in connection with tax litigation, judicial review proceedings and specialist tax commentary.
His career has therefore combined advisory work with courtroom advocacy, particularly in areas where taxation intersects with commercial and private-client law.
Setu Kamal’s Legal Career
Experience at Lincoln’s Inn
Kamal’s professional background is closely linked with tax practice at Lincoln’s Inn.
Old Square Tax Chambers lists him among its members and records his year of call as 2004. The chambers has also credited him as a contributor to Whiteman & Sherry on Income Tax, a recognised tax reference work.
His published areas of expertise have included taxation involving residence, non-residents, income tax, estate planning, VAT and other specialist tax questions.
His own professional description also highlights more than 20 years of experience dealing with intricate tax and corporate-law challenges. This broadly matches the historical professional record available about his career.
Tax and Chancery Expertise
Tax law is an especially technical branch of legal practice because it requires an understanding of legislation, case law and the commercial circumstances surrounding a transaction.
Kamal’s career has included work involving tax disputes and judicial review. A 2024 High Court judgment, for example, identified him as counsel in proceedings involving Apricot Umbrella Ltd, ABC Umbrella Ltd and Dalespay Ltd in challenges concerning HM Revenue & Customs.
This demonstrates the type of complex public-law and taxation disputes in which he has been involved.
Setu Kamal Age
The exact date of birth of Setu Kamal is not prominently published in his professional biographies.
However, a company-information record derived from Companies House data lists him as born in March 1980. If that information is accurate, he would be 46 years old in 2026. Because his precise birth date has not been independently established through a primary biographical source, this should be treated as an approximate age rather than an officially confirmed birthday.
For readers searching for “Setu Kamal age”, the most responsible answer is therefore that publicly available corporate information indicates a March 1980 birth year.
Setu Kamal Family
Information about Setu Kamal’s family is limited.
Unlike public figures who regularly discuss their personal lives, Kamal’s public profile has primarily focused on his legal career, tax work and professional disputes. Reliable sources do not provide a detailed account of his parents, siblings, wife or children.
It would therefore be inappropriate to speculate about his family background or private relationships.
The available public record is much stronger when it comes to his professional activities than his personal life. This distinction is important when researching a barrister whose public profile is principally based on legal expertise.
Setu Kamal Net Worth
There is no reliable, independently verified public figure for Setu Kamal’s net worth.
Tax barristers can earn substantial professional fees, particularly when handling specialist commercial or tax disputes. However, professional earnings do not provide sufficient evidence to calculate an individual’s personal wealth.
Company ownership, professional income and assets are also different concepts. Without verified financial statements covering his personal assets, investments, property and liabilities, publishing a precise net-worth figure would be speculative.
Consequently, searches for “Setu Kamal net worth” should be treated cautiously. Any specific figure circulating online should not be presented as fact unless it can be supported by credible financial documentation.
Setu Kamal Wikipedia
There does not appear to be a well-established Setu Kamal Wikipedia biography providing the type of detailed personal profile available for some prominent public figures.
This means Wikipedia should not be treated as the principal source for information about his career, age or professional status.
For a legal professional such as Kamal, primary and authoritative sources are considerably more useful. Court judgments, professional regulatory records and established legal publications provide stronger evidence than unsourced biography websites.
The 2026 High Court Case
One of the most significant developments in Kamal’s recent public profile came through Kamal v Tax Policy Associates Ltd and another.
The case concerned an article published by Dan Neidle and Tax Policy Associates about tax avoidance and Arka Wealth. Kamal brought claims involving libel and malicious falsehood. The matter eventually reached the High Court’s King’s Bench Division.
On 11 March 2026, Mrs Justice Collins Rice handed down judgment. The court granted summary judgment on the libel claim and struck out aspects of the case. The judgment also concluded that the proceedings met the statutory definition of a SLAPP, or strategic lawsuit against public participation, under the relevant legislation.
This was an important development in the UK’s evolving legal framework concerning public-interest journalism and litigation.
It is important, however, to distinguish the court’s findings from allegations made in commentary surrounding the case. The judgment itself is the appropriate source for understanding what the court decided.
Setu Kamal’s Current Professional Status
Another major development occurred in 2026 when the Bar Standards Board (BSB) announced an interim suspension.
According to the BSB, Kamal was initially suspended with immediate effect on 6 March 2026. Following an interim suspension hearing on 26 March, the suspension was set to continue until 30 September 2027, unless the relevant matters were concluded earlier or a disciplinary tribunal directed otherwise.
The BSB has not publicly set out the underlying allegations in its announcement. Therefore, it would be inaccurate to describe any unproven allegations as established misconduct.
The suspension is an important part of his current professional status and should be distinguished from his earlier career achievements.
Why Setu Kamal Remains a Subject of Interest
Kamal’s profile is unusual because his career combines long-standing specialist tax experience with a series of highly public legal and regulatory developments.
His earlier professional work demonstrates experience in a technically demanding area of law. His contribution to tax literature and involvement in significant tax disputes add to that professional history.
At the same time, the 2026 High Court judgment and BSB suspension have substantially changed the context in which his career is now discussed.
For anyone researching Setu Kamal, it is therefore important to consider both sides of the public record: his established legal career and the recent court and regulatory developments.
Conclusion
Setu Kamal has built a career around specialist UK tax and Chancery law, with more than two decades between his call to the Bar in 2004 and the major developments that brought him wider public attention in 2026.
His professional record includes work at Lincoln’s Inn, involvement in complex tax litigation and contributions to recognised tax literature. At the same time, his recent High Court proceedings and interim suspension represent significant developments that must be included in any up-to-date biography.
Questions about Setu Kamal age, family, net worth and Wikipedia require particular care because reliable public information is limited in these areas. The strongest evidence remains his professional record, court judgments and regulatory announcements.
Taken together, these sources provide a clearer and more balanced picture of a specialist tax barrister whose long legal career has entered a particularly significant and closely scrutinised period.